

The Week Ahead
SEQH Capital Research | Week of September 7, 2026
Happy Labor Day. We’re publishing this week’s edition on Monday instead of our usual Sunday slot in observance of the holiday, normal Sunday cadence resumes next week. We hope you’re taking the long weekend to recharge before markets reopen tomorrow.
Here’s what’s on our desk this week.
1. Research Releasing This Week
Wednesday: Hollow-Core Fiber and the Amplifier Refresh Cycle
Microsoft ramped hollow-core fiber production with Corning and Heraeus in July 2026, claiming up to 47% faster transmission and roughly a third lower latency versus standard single-mode fiber. Hollow-core fiber carries a different attenuation and dispersion profile than glass fiber, meaning the amplifiers and transceivers tuned for legacy EDFA designs are not drop-in compatible. We see this setting up a coming refresh cycle in amplifier and optics content specifically for campus and metro hyperscaler links. Wednesday’s report maps that opportunity against Lumentum’s (LITE) and Coherent’s (COHR) fiber-optics and amplifier product lines before it becomes market consensus.
Saturday: Nuclear’s Hidden Balance Sheet
Our flagship weekend release is the first systematic comparison of DOE Title 17 loan guarantees, Price-Anderson liability caps, and IRA 45U/48E credit monetization across Energy Fuels (UUUU), Oklo (OKLO), NuScale Power (SMR), NANO Nuclear Energy (NNE), and ASP Isotopes (ASPI). We quantify the effective cost-of-capital advantage these federal backstops confer, and identify which names carry the most exposure if that policy support shifts.
2. Major Market Events to Watch
Equity, bond, and futures markets are closed today for Labor Day. Once trading resumes, the calendar is front-loaded toward inflation data heading into next week’s Fed decision.
Tuesday, September 8: July Consumer Credit; Treasury announces 3-year note and 26-week bill auctions. Capital Markets Day (ASPI)
Wednesday, September 9: 10-year note auction. The prior 10-year sale in August priced at the highest yield since the financial crisis, so demand here is worth watching given ongoing supply pressure.
Thursday, September 10: August Producer Price Index (8:30 AM ET), Existing Home Sales, and a 30-year bond auction.
Friday, September 11: August Consumer Price Index (8:30 AM ET), the marquee print of the week. Consensus expects headline CPI up 0.4% month over month, holding the annual rate near 3.4%, with core prices up a slower 0.2%, cooling the annual core rate to roughly 2.3% (Cleveland Fed inflation nowcast). The preliminary University of Michigan Consumer Sentiment read for September also lands Friday.
The setup matters because last Friday’s August jobs report ran hot, payrolls up 162,000 versus a 55,000 consensus estimate, with unemployment holding at 4.1% (Reuters). That print pushed short-term rate futures to price roughly 59% odds of a rate increase at the Fed’s September 15-16 meeting, up from about 55% beforehand. This week’s CPI print is the last major data point before that decision, so a hot or cool surprise on Friday should move the hike odds meaningfully in either direction. The FOMC meeting itself, with a fresh Summary of Economic Projections and press conference on Wednesday, September 16, sits just outside this week’s window but is very much on our radar.
3. Quant / Advanced Analytical Data for the Upcoming Week
A data snapshot on the names underpinning this week’s two research releases, plus broader positioning context heading into the CPI print and next week’s Fed decision.
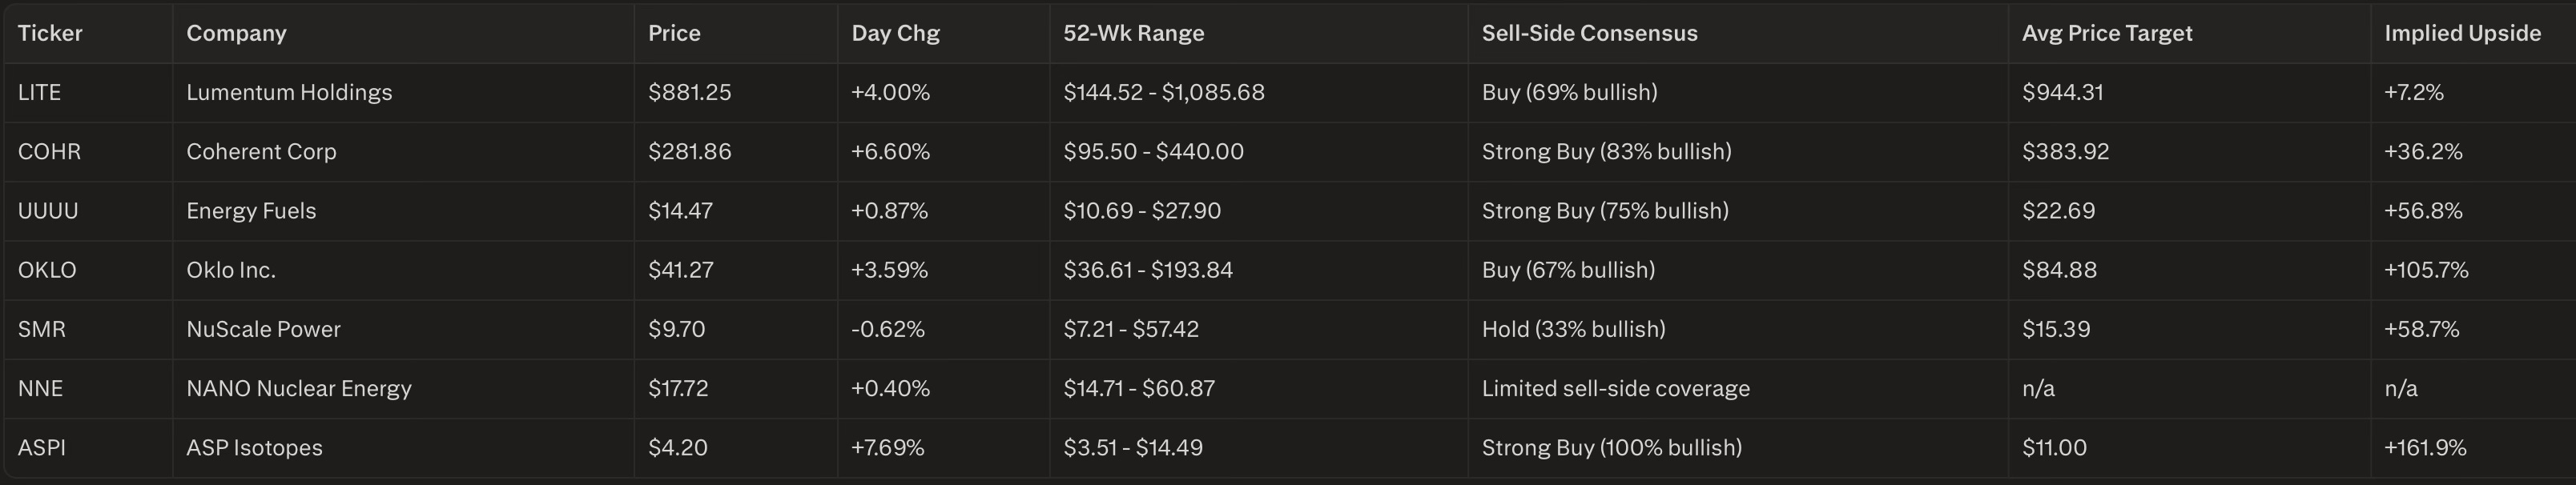
Prices reflect the latest available close. Percentage changes are single-session moves, not weekly performance.
A few things stand out. LITE and COHR have already re-rated sharply, both are trading well off their 52-week lows, with LITE’s average sell-side target now sitting only modestly above spot, so the fiber-optics thesis is arguably more about which specific product lines capture the hollow-core refresh than about the sector re-rating further from here. The nuclear complex tells a different story: every name in Saturday’s coverage list except SMR carries a Buy-or-better consensus, and the average targets across UUUU, OKLO, and ASPI still imply substantial upside from current levels, meaning the market has not yet fully priced the federal backstop dynamics we’re about to quantify.
On the volatility side, the VIX is sitting at 15.30 (up 5.30% on the session), still near the low end of its 52-week range of 13.38 to 35.30. That is a fairly complacent starting point for a week carrying an inflation print, two long-duration Treasury auctions, and a live Fed decision the following week. The Global X Uranium ETF (URA), a reasonable proxy for nuclear-sector sentiment, is at $46.06 (+0.79%), well above its 52-week low of $37.18 but still off its high of $62.28, leaving room to react to Saturday’s report either way.
4. Upgrade to a Paid Membership
Free subscribers get our takeaways. Paid members get the full research, the data behind it, and direct access to the desk.
Paid ($20/month) includes:
Full-length publication of every report, including Wednesday’s amplifier refresh cycle note and Saturday’s Nuclear’s Hidden Balance Sheet, on release day rather than in preview form
The underlying quant models and data files behind flagship reports, including the Title 17, Price-Anderson, and 45U/48E comparison framework
Complete access to the SEQH research archive
Our running, dated model portfolio for full accountability
Direct access to the analyst desk for questions on published research
Custom research requests within our coverage universe
Priority scheduling for bespoke sector briefings
If you’re ready to move from free previews to full access, upgrade here: Upgrade to SEQH Capital Research
SEQH Capital Research
Institutional-grade research for the nuclear, uranium, and technology infrastructure sectors.